Why Android Dominates Global Mental Health App Downloads
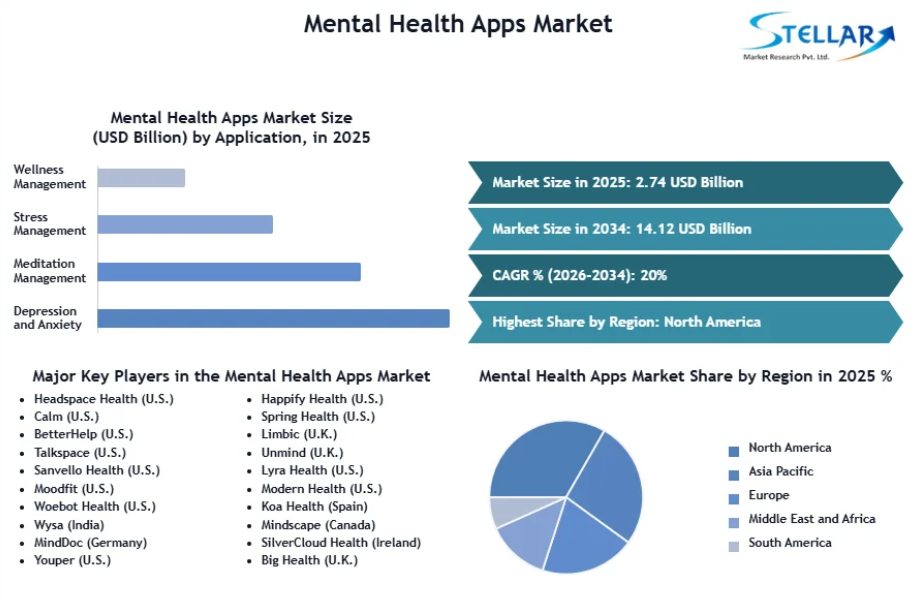
The global Mental Health Apps Market is experiencing a profound paradigm shift driven by enterprise-sponsored digital wellness, generative artificial intelligence integration, and rigorous clinical validation frameworks, according to a comprehensive intelligence report released by Stellar Market Research. Valued at USD 2.74 billion in 2025, the market is projected to expand significantly, accelerating through the forecast period to reach an estimated USD 29.23 billion by 2034 at a compound annual growth rate (CAGR) of 20.0%. As worldwide health systems grapple with surging clinical demand and corporate buyers seek scalable solutions to mitigate employee burnout, mobile-first behavioral health platforms are evolving from simple meditation tools into evidence-based clinical intervention ecosystems.
The digital therapeutics landscape has moved past the direct-to-consumer app-store boom of the early 2020s. Today, the core market transformation centers on enterprise-paid access models and clinically validated AI companions that bridge the gap between primary self-care and professional psychiatric intervention. High customer acquisition costs (CAC) in traditional consumer channels have pushed leading market players to pivot toward business-to-business (B2B) employer contracts and insurance-reimbursable digital health pathways (such as Germany’s DiGA model and expanding U.S. CMS reimbursement codes).
Key Findings from the Report
Market Valuation & Trajectory: The global mental health apps market is valued at USD 2.74 billion in 2025, scaling dynamically through 2034 at a 20.0% CAGR.
Dominant Platform Segment: Android retained the largest platform revenue share, propelled by extensive global device penetration, affordability across emerging economies, and widespread accessibility for diverse demographic groups.
Fastest-Growing Segment: The depression and anxiety management application segment represents the fastest-growing category, fueled by rising clinical diagnoses and corporate emphasis on targeted mental health interventions.
Leading Regional Market: North America commanded the primary regional share in 2025, underpinned by mature digital health infrastructure, widespread employer-sponsored health benefits, and early insurance reimbursement frameworks.
Emerging Regional Epicenter: Asia-Pacific stands out as the fastest-growing regional market, driven by skyrocketing smartphone penetration, government-backed mental health initiatives, and progressive destigmatization campaigns in India, China, and Japan.
Subscription Model Dynamics: Freemium acquisition models capture significant initial user volume, whereas enterprise-paid and premium subscription models deliver the highest revenue growth and retention rates.
Investment Relevance: Venture capital and strategic M&A activity are increasingly rewarding platforms that demonstrate clinical trial validation, robust data privacy compliance (HIPAA, GDPR), and seamless integration into traditional healthcare delivery networks.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/Mental-Health-Apps-Market/199
Market Drivers and Restraints
Drivers
Surging Corporate Wellness Adoption: Enterprise-paid mental health benefits are rapidly expanding as employers recognize the direct correlation between untreated employee stress, absenteeism, and diminished productivity. Per-employee-per-month (PEPM) corporate contracts provide stable, recurring revenue streams that insulate developers from consumer marketing volatility.
Proliferation of Generative AI & Conversational Agents: Advanced natural language processing models allow applications to offer 24/7 personalized coping mechanisms, real-time journaling prompts, and low-risk cognitive reframing, dramatically boosting user engagement and adherence.
Favorable Regulatory & Reimbursement Pathways: Institutional validation through national digital health frameworks—such as government-backed assessment cohorts in Canada, clinical trial registries in Japan, and statutory health insurance approvals in Europe—is transforming apps from lifestyle add-ons into recognized clinical tools.
Restraints
Data Privacy and Security Vulnerabilities: Mental health applications handle highly sensitive personal and clinical data. Breaches or perceived lapses in data governance can trigger severe regulatory penalties under HIPAA and GDPR, destroying user trust and stalling enterprise adoption.
High Customer Acquisition Costs (CAC) in Consumer Segments: Intense competition within app stores combined with privacy policy shifts (such as identifier tracking restrictions on mobile operating systems) has inflated acquisition expenses for standalone, direct-to-consumer subscription models.
Technology, Regulation, and Sustainability Trends
The modernization of mobile mental health is underpinned by major technological and regulatory milestones. On the technology front, developers are moving beyond static rule-based chatbots toward secure generative AI models fine-tuned on peer-reviewed psychiatric protocols, ensuring safe, context-aware user interactions. Edge-computing capabilities also allow real-time sentiment analysis from wearable biometric data while safeguarding user confidentiality on-device.
From a regulatory standpoint, healthcare authorities worldwide are tightening evaluation standards. National commissions are implementing rigorous vetting frameworks that audit apps for clinical efficacy, data encryption, accessibility, and cultural suitability. Simultaneously, environmental, social, and governance (ESG) considerations are prompting institutional investors to evaluate digital health portfolios based on health equity, linguistic inclusivity, and equitable access for underserved rural and minority communities.
Regional Insights
North America: Maintaining its leading market position, North America benefits from robust venture capital backing, high smartphone adoption, and proactive self-insured employers partnering with digital health innovators to curb rising medical claims. Regulatory milestones, including specialized reimbursement codes for digital therapeutics, continue to solidify the region's commercial maturity.
Asia-Pacific: Registering the fastest regional growth rate, Asia-Pacific is propelled by monumental public health programs. For instance, India’s Ministry of Health and Family Welfare has expanded the Tele-MANAS digital framework across dozens of regional cells and languages, while Japanese startups and clinical registries aggressively deploy advanced virtual reality and mobile mental health solutions to address urban stress and depression.
Recent Industry Developments
Sword Health (2026): Launched Dawn, its first direct-to-consumer AI-based mental health application, delivering immediate personalized behavioral support and clinical care navigation, expanding the company's addressable digital therapeutics market.
Headspace (2025): Introduced advanced voice interaction capabilities for Ebb, its empathetic AI companion integrated directly into the Headspace application, scaling conversational engagement and personalized mindfulness pathways for global users.
Wysa & Imperial College London (2026): Initiated a USD 7.2 million, Wellcome-funded collaborative project to adapt and rigorously scale an AI-enabled digital mental health program, bridging academic clinical research with real-world app deployment.
Calm (2025): Partnered with Google to launch a dedicated application for Android XR, introducing over 50 optimized immersive meditations, 3D breathing exercises, and 360-degree environments across the wider extended reality device ecosystem.
LunaJoy Health (2024): Successfully secured USD 4.2 million in financing to accelerate the development of specialized digital health applications for maternal mental health care, concurrently launching its integrated LunaCare program.
Competitive Landscape
The global mental health apps market features a highly competitive blend of established digital wellness leaders and specialized health-tech innovators. Key market participants include Calm, Headspace, Talkspace, BetterHelp, Wysa, Youper, K Health, and Sword Health.
Leading players are executing multi-pronged growth strategies centered on enterprise B2B partnerships, multi-language localization for emerging international markets, and clinical validation studies. Rather than competing solely on meditation content, market leaders are actively acquiring specialized clinical platforms, embedding conversational generative AI, and securing integration agreements with major health insurers and hospital networks to lock in long-term enterprise distribution.
Analyst Commentary
"The mental health apps market has crossed a critical maturity threshold. We are no longer observing a simple proliferation of lifestyle wellness downloads; the industry is consolidating around clinical rigor, verifiable outcomes, and scalable B2B enterprise channels. Providers that successfully merge empathetic AI engagement with airtight data privacy and seamless clinical escalation pathways will capture the lion's share of this multi-billion-dollar transformation."
— Senior Research Analyst, Stellar Market Research
Future Outlook
Over the forecast period through 2034, the mental health apps market will experience accelerated institutional convergence. Demand will increasingly shift toward outcome-based contracts where enterprise buyers and insurers tie app reimbursement directly to measurable reductions in employee anxiety, stress, and clinical depression rates. Technology will evolve toward ambient, wearable-integrated mental wellness monitoring that detects early physiological markers of distress. While competitive pressures will weed out unverified lifestyle apps, well-capitalized platforms that achieve regulatory clearance and enterprise trust are positioned for exceptional long-term expansion.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/Mental-Health-Apps-Market/199
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656
Author Bio
Article Comments
No Comments!
At present there are zero published comments on this article.
Similar Articles
Search Pages
Article Categories
There are zero sub-categories in this parent category.
There are zero sub-categories in this parent category.